Delinquency rates climb 40 per cent in Alberta
Posted Aug 18, 2016 8:19 am.
Last Updated Aug 18, 2016 8:23 am.
This article is more than 5 years old.
Low oil prices and job cuts in Alberta are keeping many from paying back loans.
Delinquency rates have climbed 40.3 per cent in the last year, while the average Calgarian is juggling $28,572 non-mortgage debt.
Although the jump is significant it is something we have seen in the past during rough patches in the economy.
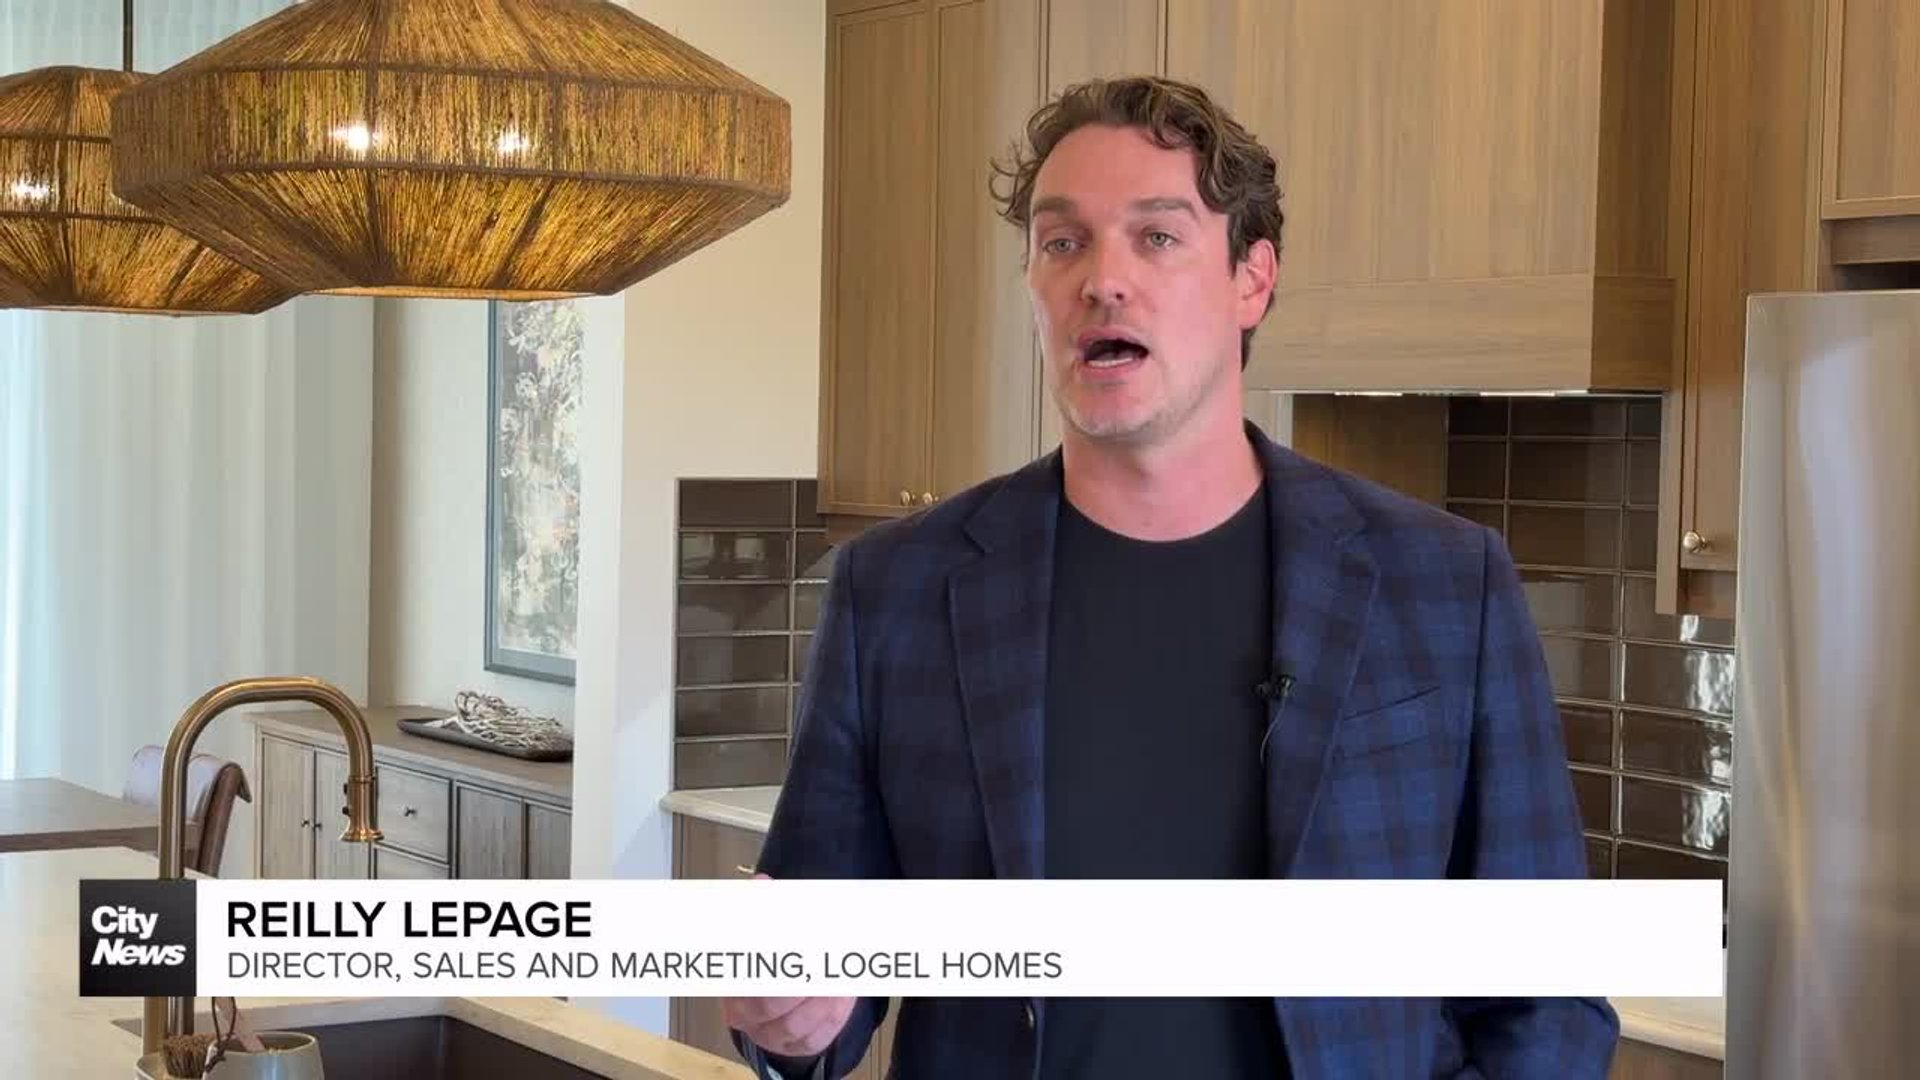
Regina Malina, Senior Director of Decision Insights at Equifax Canada says we shouldn’t be sounding the alarm just yet.
“Even though the changes sound significant, the actual delinquency rates are still very low (1.1 per cent in Calgary),” she said.
Malina says the situation with oil prices is a persistent one. While she’s confident consumers will adjust to the new reality, it’s not clear how long it will take.
Some of the current debt is being carried over from a couple years ago, and Albertans are racking up more debt in auto loans and mortgages. Debts, it seems, we can’t pay back as quickly as we could before.
“At some point within a couple of years, I think definitely these increases should stop, and if there are changes in the economic situation in interest rates, perhaps more in a negative way as far as delinquency rates are concerned, or in oil prices, if they start to rebound at a higher speed, than we might see stability a little sooner,” Malina said.
While seniors have collected more debt in the past year, they seem to be better at paying it back than those aged 18-25. That group saw an 11 per cent increase in delinquency in the last 12 months, across the country.
It’s not completely unexpected, but Malina says now is a good time for a gentle reminder to young millennials to brush up on their money management skills.